Relocating to Miami in 2026 is a financial decision that happens to involve a house. That order matters, and it's the part most out-of-state buyers get backwards.
The buyers who walk into a Miami closing happy aren't the ones who fell in love with a listing on Zillow at 11 p.m. on a Tuesday. They're the ones who underwrote the move the way you'd underwrite any other major capital decision: tax math first, lifestyle and neighborhood fit second, the specific home third. I started in real estate finance in 2006 as a mortgage loan originator before getting licensed in 2018, and that ordering is the single biggest thing my finance background has changed about how I work with relocation clients.
This is the version of the conversation I have with out-of-state buyers before they fly down for their first weekend of showings. It covers why the move still pencils for the right buyer, the Florida tax math people get wrong, how to choose a Miami neighborhood from a distance, financing realities for non-residents, and the hidden costs every relocation buyer should underwrite before they fall in love with a property.
For anyone considering a move to Miami, our Relocation Guide offers a helpful starting point.
Why People Are Still Moving to Miami in 2026
The Miami relocation story isn't slowing down, and the buyer mix is broader than the headlines suggest.
The pull is the same combination it's been for the last several years: no Florida state income tax, a strong concentration of finance and tech employers building out Miami offices, year-round outdoor living, and a real-estate market that, for all the noise, still rewards thoughtful long-term ownership in the right submarket. What's changed in 2026 is the discipline required. The "buy anything, anywhere, today" energy of 2021 and 2022 is gone. The buyers winning now are the ones picking the right neighborhood, the right product type, and the right price tier on purpose, not by default.
For broader market context on where the year is heading, my 2026 Miami real estate forecast is the right place to start before you set a budget.
The Florida Tax Math Out-of-State Buyers Actually Need to Run
The "no state income tax" line is technically true and meaningfully incomplete.
Florida has no state personal income tax, which is real money for high earners moving from New York, New Jersey, California, Illinois, or Massachusetts. But the move only delivers that benefit cleanly if you actually establish Florida residency, which is a separate set of steps from buying a home. That includes filing a Declaration of Domicile, getting a Florida driver's license, registering to vote in Florida, updating estate planning documents, and being able to show that your day-to-day life genuinely happens here. Buyers who keep one foot in their old state, especially New York, often get audited and find themselves owing tax in the state they thought they'd left.
Property tax math is the other piece relocation buyers underestimate. Florida's homestead exemption is generous if the property is your primary residence, but it does not transfer at full value the day you close. New owners reset to the current assessed value, not the prior owner's protected base, which can mean a property tax bill meaningfully higher than what the listing's prior tax history suggests. For second-home and investment buyers, none of the homestead protections apply, and the carrying cost math has to reflect that.
This is also where insurance comes in. Miami homeowner's insurance, particularly for waterfront, ground-floor, and older condo product, has moved up significantly in recent years. Flood zone status, elevation, building age, and roof age all feed into the premium, and a quote that came in tight on one home can come back twice as high on another two blocks away.
The point isn't that the tax move doesn't pencil. For most high-earner relocations into Miami, it absolutely does. The point is that running the math honestly, including property tax reset, insurance, HOA where applicable, and residency-establishment friction, is what separates a clean relocation from a frustrating one.
How to Pick a Miami Neighborhood From a Distance
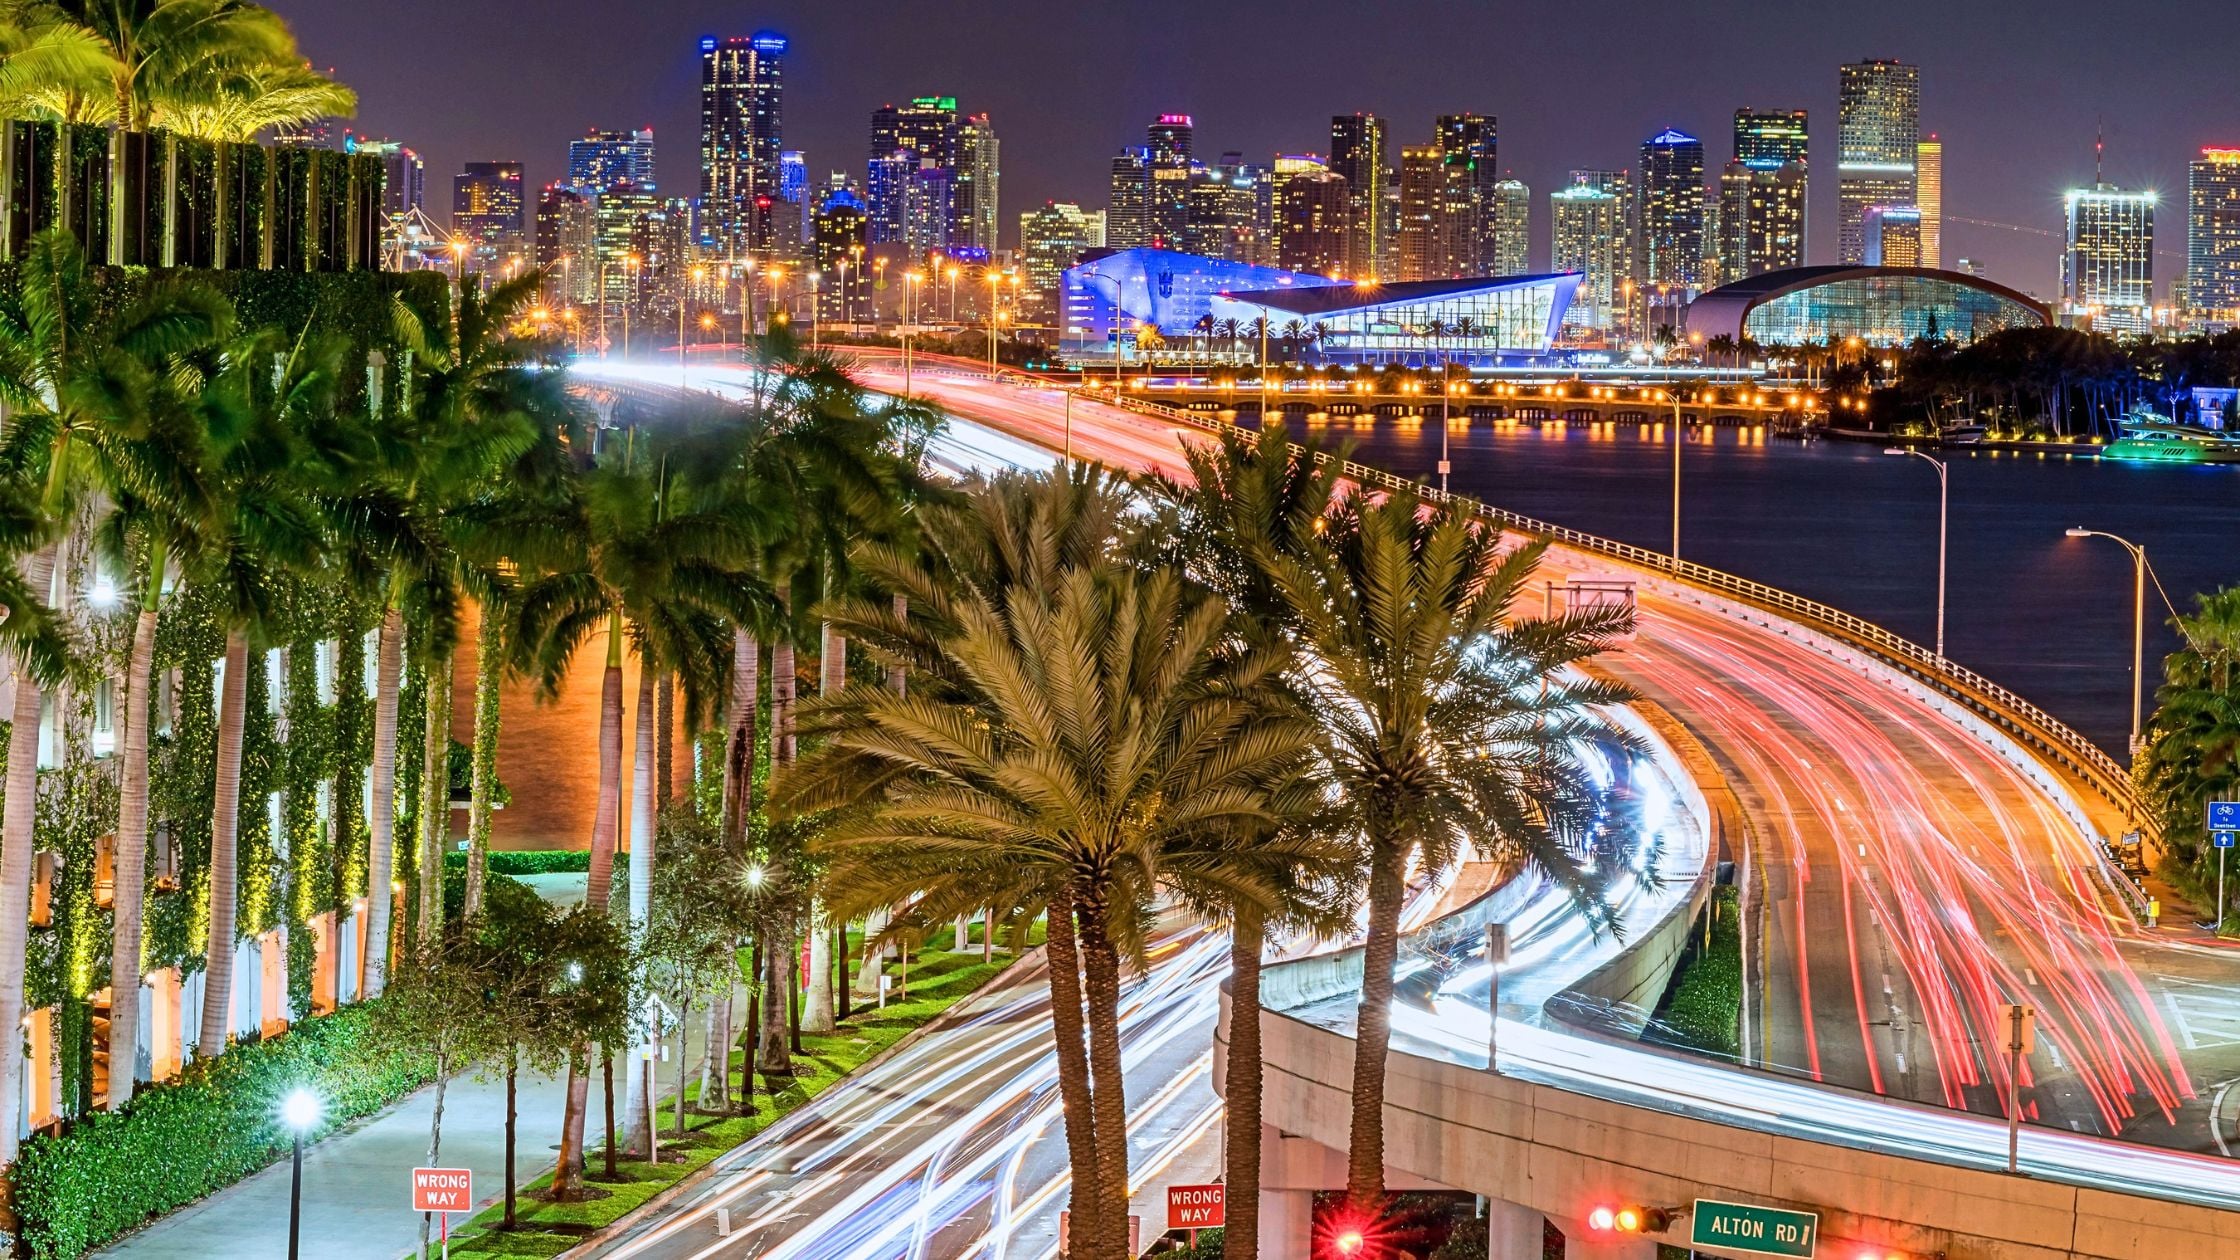
Miami isn't one market, and "Miami" on a national headline can mean ten very different lifestyles depending on where you actually land.
Coral Gables is family-driven, school-driven, tree-canopied, and built. Brickell is high-rise, walkable, professional, and dense. Coconut Grove is bayfront, leafy, and quiet. South Beach and Miami Beach are island lifestyles with their own rhythms. Edgewater is bayfront new construction. Pinecrest, Palmetto Bay, and the south Dade neighborhoods are larger lots, single-family, and more suburban. Sunny Isles and Bal Harbour skew international-luxury. Each of those is a different home, a different commute, a different school system, and a different price-per-square-foot reality.
Explore the Miami neighborhood guides
Use these neighborhood guides to narrow your shortlist before your first scouting trip.
- Brickell: high-rise, walkable condo living near the financial district
- Edgewater: bayfront condos and new construction north of Downtown
- Coconut Grove: bayfront, leafy, and quieter, with homes and townhouses
- Coral Gables: tree-lined streets and Mediterranean-style homes
- The Roads: a historic 1920s street grid minutes from Brickell
- Shenandoah: historic single-family homes near Coral Gables and Brickell
- Silver Bluff: a central residential neighborhood near Shenandoah and Coconut Grove
- South Miami: a small-city feel with single-family streets and a walkable downtown
- Pinecrest: larger lots, single-family homes, and a suburban pace
The most common mistake I see out-of-state buyers make is treating "Miami" as a single decision and then trying to choose a neighborhood from a generic search. The better sequence is the reverse: start by being honest about your priorities (school zones, commute, walkability, water access, building amenities, privacy, single-family vs. condo), and let those filter the neighborhood list down to two or three candidates before you ever look at specific listings.
For a structured tour of how Miami's submarkets compare on lifestyle, the Miami neighborhood lifestyle guide is the cleanest starting point I have on the site.
Condo or Single-Family Home: Which Fits Your Relocation?
The home type you choose shapes your monthly costs as much as the neighborhood does. Condos in Brickell, Edgewater, and Downtown suit buyers who want walkability, building amenities, and a lock-and-leave setup, especially while they are still splitting time with the Northeast. Single-family homes in Coral Gables, Pinecrest, South Miami, and Coconut Grove suit buyers who want a yard, more space, and fewer shared decisions with an association.
Each path comes with its own homework. For condos, review the association's budget, reserves, and meeting minutes, and ask whether the building has completed the milestone inspections and structural integrity reserve studies that Florida's condo safety laws now require for many buildings. For single-family homes, get insurance quotes early, check the flood zone and elevation certificate, and budget for roof, pool, and landscaping upkeep.
Schools and School Zones for Relocating Families
For families moving from the Northeast, schools often decide the neighborhood. Public school assignments in Miami are handled by Miami-Dade County Public Schools and are based on a home's address, so two homes a few blocks apart can be zoned for different schools. The district also offers magnet and choice programs with their own application timelines, and the area has a wide range of private schools.
Before you write an offer, confirm the zoned schools for that exact address directly with the district. If you are considering magnet or private options, check application deadlines early, since they may not line up with your moving date. Each neighborhood guide above includes a Schools In The Area section to start your research.
Financing a Miami Home as an Out-of-State Buyer
The financing landscape for relocation buyers in 2026 is more nuanced than it was three years ago, and lender selection matters more than it used to.
A few realities to plan around. Out-of-state primary-residence purchases are still standard business for most lenders, but the documentation work tends to be heavier than for in-state buyers. You'll be asked to substantiate the relocation (employer letter, transfer offer, residency intent), and the appraisal turn times in Miami can be slower than in less competitive markets. For second-home and investment-property purchases, expect a higher down payment requirement, a slightly higher rate, and stricter reserves.
The other piece relocation buyers should think about up front is rate-lock strategy. Miami transactions can stretch out, especially in pre-construction and luxury single-family. A 60-day lock that worked for a quick condo close may not cover the timeline of a custom-built single-family or a pre-construction conversion. Talk to your lender about extended-lock options before you write an offer, not after.
This is the area where the finance background does the most for my clients. I've sat on both sides of a mortgage closing, and the difference between a strong lender for a Miami relocation and a generic out-of-state lender shows up in the timeline, the rate, and whether the deal closes cleanly.
Buying From a Distance: Visits, Offers, and the Contingencies That Matter
Most out-of-state purchases I work on involve one or two scouting trips and a closing trip, sometimes only the closing trip if the buyer has done their homework.
What works: a structured first visit focused on neighborhoods, not properties. Drive the streets, sit in the cafes, do the morning commute, walk the schools, see what the area actually feels like at 7 a.m. and at 9 p.m. By the time you're looking at specific homes on a second visit, you should already know which two or three submarkets you're choosing between. That dramatically tightens the search and reduces the number of "I'm not sure" homes you tour.
What also works: writing offers with the right contingencies for a relocation buyer. Inspection contingency is non-negotiable. Insurance and elevation-certificate contingencies matter for any waterfront or older-construction product. For condo purchases, a financial-review contingency on the building's reserves and special assessments is critical in 2026, because building financials are doing real work in valuations right now.
For a deeper read on the buying mechanics specifically for non-residents, my out-of-state and international buyer guide covers the process step by step.
The Hidden Costs to Underwrite Before You Sign
Beyond the purchase price, the costs that catch relocation buyers off guard are roughly the same every time.
Property taxes that reset to current assessed value, not the seller's protected base. Homeowner's insurance plus, where applicable, separate flood and wind policies. HOA dues for condos and gated communities, plus the very real possibility of special assessments in older buildings working through reserve studies and recertification. Hurricane preparedness costs (impact windows, generators, shutters) that don't show up on a Zillow listing. Higher utility bills than buyers from cooler climates expect, particularly through the late summer. And the lifestyle costs (boat slip, club, beach access, gym memberships) that often quietly become part of the carrying cost of living in a particular neighborhood.
None of this is a reason not to relocate. It's a reason to run the carrying-cost math up front, before you anchor to a specific home, so the home you choose actually fits the financial picture you're moving into.
Thinking About Relocating to Miami This Year?
Planning a move from New York, New Jersey, Boston, or elsewhere in the Northeast? As a Miami real estate advisor with SERHANT., I help out-of-state buyers narrow down neighborhoods, plan their scouting trips, and buy with confidence from a distance. Email me at [email protected] and we can start building your relocation plan.